The AI Chip Selloff Reaches Asia: Kospi Drops More Than 5% After the Report on OpenAI's Revenue
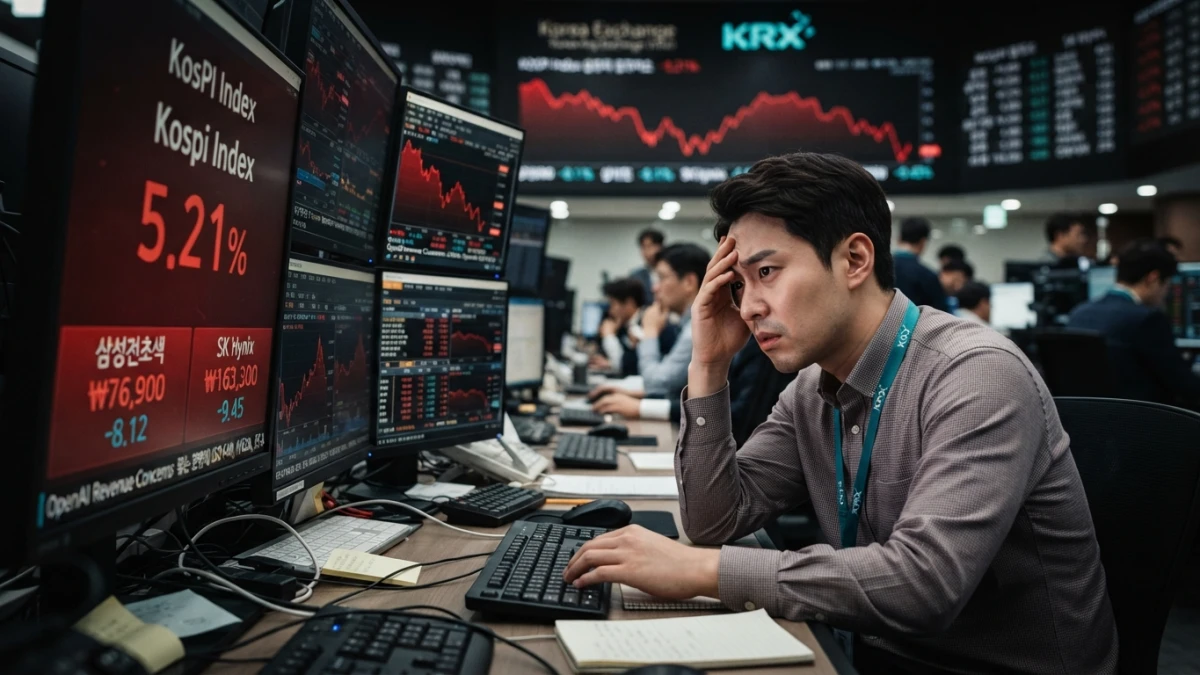
A Financial Times report on OpenAI's annualized revenue was enough to spark an AI chip selloff: tech stocks fell in the United States first and then in Asia, where the Kospi lost more than 5% on October 13 with Samsung and SK hynix leading the losses.
The AI Chip Selloff, in Order (and in Five Days)
This was not a single event, but a chain of three links in less than a week.
October 8: The Report on OpenAI's Revenue
The Financial Times reported that OpenAI's annualized revenue was around $50 billion at the end of September, roughly $20 billion below the figure near $68 billion that had been circulating weeks earlier. According to outlets such as CNBC and Axios, the discrepancy has to do with how each AI company accounts for its sales, not with an actual drop in sales.
October 9: US Chip Stocks Fall and the Debate Opens
Names like Nvidia, Micron, Oracle and CoreWeave fell. Part of the financial press called the reaction overblown, because the underlying business of the memory suppliers had not changed overnight.
Read also
October 12 and 13: Asia's Turn, With the Kospi Below 6,000
On Monday, October 12, Korea's Kospi index fell around 3% to 4%; on Tuesday, October 13, it ended down more than 5%, near 6,035 points and after hitting intraday lows below 6,000, according to the closing figures gathered by the press. Samsung Electronics and SK hynix led the losses, with declines of 6% to 10% depending on the time of day.
Seoul's Sidecar: What It Is and Why It Kicked In
The Korean exchange triggered a sell sidecar, a mechanism that temporarily halts orders when the market becomes disorderly. It is a stress indicator, not a cause.
What "20 Billion Less" Means (and Why It Is More Complicated)
Annualized Revenue, or Run-Rate: the Metric Everyone Misreads
Annualized revenue is what a company would bill in a year if it repeated the month it just closed. It is not an audited figure or a fixed projection: it is an extrapolation, which is why two ways of counting it can differ by tens of billions.
Counting It Differently Is Not Selling Less: What Analysts Say
Analysts quoted by the press insist the gap is one of accounting definition, not sales: the debate is about how revenue is added up.
What the Company Answered and What We Still Don't Know
A spokesperson quoted by the press said annualized revenue went from about $28 billion at the end of June to about $50 billion at the end of September, and that the company expects to reach or exceed $70 billion by the end of 2026. The exact criteria used to calculate the earlier figures remain unclear.
Why Chips Are the Thermometer of AI
HBM and DRAM: the Ingredient Behind All That Compute
AI accelerators depend on HBM memory and servers on conventional DRAM, and both compete for the same wafers. In plain terms: when demand expectations shift, the discount lands on the supplier of the ingredient first, not the final product.
Korea, Two Companies and an Entire Index
The Korean market is concentrated in two memory makers, which explains why a report on a US company's revenue moves an entire Asian index.
CXMT: the Other Reason for the Fall
The second trigger was the advance of China's CXMT, the world's fourth-largest DRAM maker, which announced mass production of its fifth-generation DRAM platform and LPDDR5X chips with more capacity per wafer. If China closes the gap in conventional memory, the oligopoly that today sustains prices loses power. In HBM, the gap remains wide.
What Has Not Changed (and Is Worth Remembering)
Memory Supply Is Still Committed and Contract Prices Are Still High
The big manufacturers keep HBM and DRAM for servers with committed capacity and rising contract prices. Micron maintains its forecast of tight supply through its fiscal 2028; we covered that chapter on this blog when Micron warned that memory will stay tighter through 2028.
Fabs Don't Shut Down After One Bad Session
A stock drop does not change a fab's installed capacity or the contracts already signed. Expansion plans being moderated if the cycle cools is a scenario, not a fact.
What This Means If You Write Code or Render
Hardware Prices: Why RAM Doesn't Get Cheaper Next Week
Memory prices are negotiated quarterly. A stock drop does not reset RAM prices the next day; at most it influences medium-term capacity decisions.
API Costs: Why Your Bill Doesn't Follow the Stock Market
The price per token is set by competition and serving capacity, not by a share price. Read our analysis of the price war between the big models for the real mechanism.
Buying Hardware or Compute: How to Read the Risk Without Drama
The useful reading is about risk, not opportunity. If the capex cycle slows, spare capacity could make compute rentals cheaper; if it holds, prices will stay high. These are conditional scenarios, not predictions.
What to Watch Over the Next Few Days
- The US inflation reading, due on Wednesday.
- Earnings and capex from the big cloud providers (hyperscalers).
- DRAM and HBM contract prices, and the capacity coming from China.
- Whether Korea's market brakes fire again, such as the sidecar.
Conclusion
One bad session is not a change in trend, and a disputed metric is not a drop in sales. What happened this week is a reset of expectations about the return on AI investment, not proof that the business is shutting down. If you follow the memory and compute cycle, we keep publishing the next chapter on this blog.