The S&P 493: Where AI Still Isn't Moving Revenue Per Worker or Margins
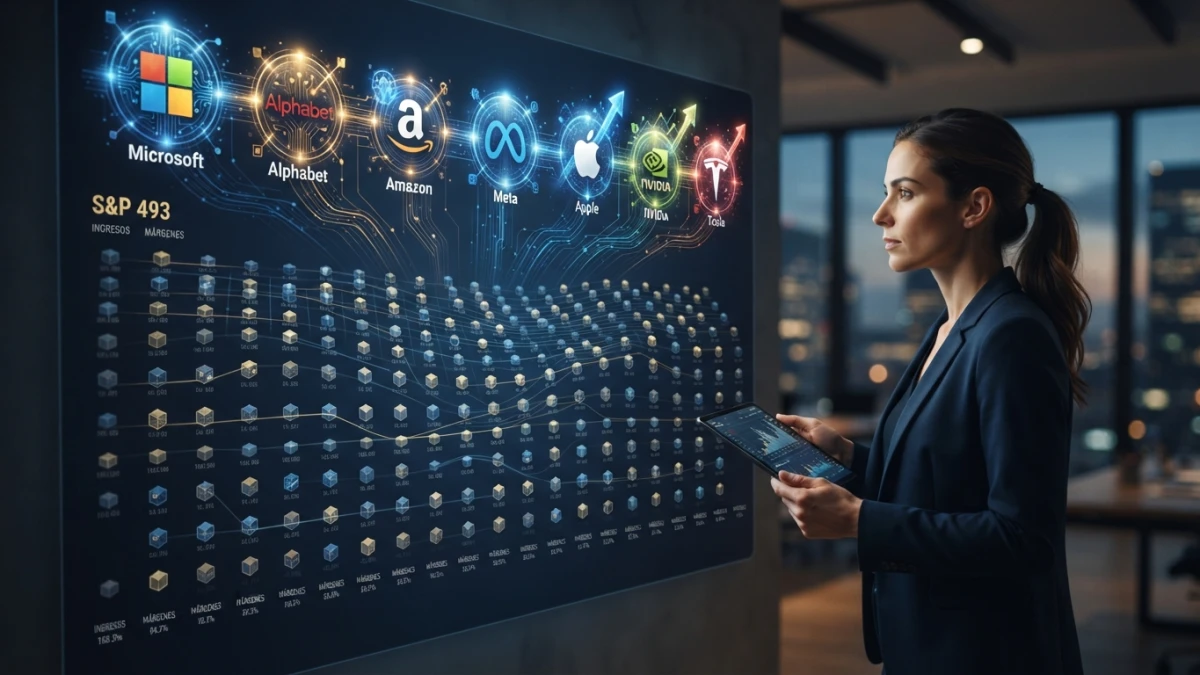
Revenue per worker and margins are rising across the Magnificent Seven and still flat across the S&P 493, per the note Torsten Slok published on Saturday. It lands three days before Microsoft, Alphabet and Amazon report earnings.
What Apollo's Note Actually Says
Torsten Slok, chief economist at Apollo Global Management, published a note on October 24 in his Daily Spark newsletter titled "No Signs of AI Payoff Outside the Tech Sector". Bloomberg and TechCrunch picked it up the next day, and Bloomberg's headline is literal: AI provides "zero payoff" to the S&P 493 outside tech.
The Split: Magnificent Seven vs. the S&P 493
The S&P 493 isn't an index you can trade: it's the S&P 500 minus Alphabet, Amazon, Apple, Meta, Microsoft, Nvidia and Tesla. It stands in for "the average company" in large-cap land, and Slok plots both worlds on the same charts.
Revenue Per Worker and Margins: The Two Flat Lines
Revenue per worker is sales divided by headcount. At the seven it rises; across the rest of the index it is flat. Margins draw the same shape. The sources say "flat", with no published percentages: what is verifiable is the direction, not the magnitude.
Read also
Productivity: No Signal in the Aggregates
This is the uncomfortable one, because it carries the underlying promise. If AI isn't moving output per hour across the economy as a whole, the spending is justified by other reasons — defensive ones, not-getting-left-behind ones — and those reasons last less time in a budget.
What the Note Measures and What It Does Not
This is where most headlines break, in both directions.
It Is Analysis, Not a Study
The note is analysis with charts, not peer-reviewed research. There is no new methodology and no company sample: there are macro series and a reading. That doesn't invalidate it, but it changes how you cite it. It is "Slok's note", not "a study shows".
An Aggregate Measure Does Not Deny Individual Cases
A flat average doesn't mean no company made money with AI: it means the gains, if they exist, don't move the aggregate. That's the distinction Digg underlines when it covers the note. "AI is useless" is as imprecise as "AI already changed everything".
Why This Note Is Not New (and Why It Still Matters)
It is neither a scoop nor a surprise. Saying so removes the scandal without removing the weight.
The Same Thesis Since June 30
Slok had already made the point in his June 30, 2026 note, picked up by Fortune in July: if margins don't improve outside tech, the risk is a "painful repricing" of AI stocks. What changes now is the evidence behind the argument and the calendar that tests it.
What Changed: The Revenue-Per-Worker Chart
That cut is the new piece. It's a blunt metric — a company can improve margins by cutting staff without gaining real productivity — but it's hard to argue with when you compare the same series across two groups of the same index over the same period. The note doesn't say "AI doesn't work": it says "the effect isn't showing up where it should show up first".
This Week's Test
It lands three days before the busiest earnings week of the year, and that isn't a calendar coincidence: it's why it was published now.
Microsoft and Alphabet, Wednesday the 28th
Both report on Wednesday, October 28 after the close, per the schedule carried by CNBC. These are the two companies where AI spending and the cloud business are most entangled: if capex rises and cloud growth slows, margin pays for it.
Amazon, Thursday the 29th
Amazon reports Thursday the 29th, with AWS at the center. Forbes reported on October 25 that S&P 500 earnings are on track to grow 29.5% this quarter; that figure is Forbes's and is cited as such. What matters isn't the total but where it comes from: if nearly all the index's earnings growth comes from seven companies, the note is confirmed by the facts themselves.
The Three Columns: Capex, Cloud and Margin
To read these results without getting lost: how much they spend (capex and compute commitments), how fast the business that charges for it grows (cloud and AI services) and what margin is left after data-center depreciation. Capex growing faster than the revenue it produces is exactly the path Slok describes, one quarter at a time.
The Data That Backs the Note, and the Data That Softens It
Three earlier studies add context. None is part of the note, and that should be said when citing them.
Record Adoption, Scarce Returns
McKinsey's State of AI 2026 reports that 40% of large organizations say they are scaling AI agents, up from 27% a year earlier. And MIT's Project NANDA, in 2025, found that close to 95% of enterprise generative AI pilots showed no measurable impact on results. A 2025 figure, not this week's. Together they describe the same thing: lots of adoption, little measurement.
The Developer Case: 19% Slower With AI
METR published a randomized trial in 2025 with experienced open-source developers: with AI tools they finished tasks 19% slower, even though they believed they had been faster. It doesn't measure perception, it measures time to a finished task. The gap between what you believe and what you measure is the finding.
What It Means for People Building With AI
Let's come down from macro to the invoice, which is where this gets decided for a small team.
Cost Per Task Ends Up in the Budget
AI spending hits the income statement like anything else: tokens, licenses, review time for whatever the model produces. Tom's Hardware ties the note to rising token costs and the pressure they put on the margins of companies using AI. The same theme came up when we wrote about Kimi K3.1 Pro's pricing and cost per task.
How to Measure Your Own Without Waiting for an Economist
The metric that survives a budget cut isn't "adoption", it's cost per finished task: tokens consumed, minutes of human review and tasks closed in the period. If that number falls month over month, the tool pays for itself; if it rises, you have a process problem dressed as a tool.
Worth looking at the other side: the same firm behind the note, Apollo, was leading the $40 billion debt deal in October so SpaceX could buy Nvidia chips, as we covered in AI getting financed like infrastructure. The money never stopped coming in; what's missing is it coming out the other side of the balance sheet. This blog argued in general terms years ago that AI improves productivity (improve your productivity with AI at work): the note doesn't refute that case by case, it says the average doesn't show it yet.
Conclusion
The note leaves a different question than the one it seemed to pose: adoption is no longer in dispute, the return is, and it is measured per finished task. This week three companies are obliged to answer with numbers, and you can answer in your own team with a spreadsheet and three columns. None of this is investment advice, and it doesn't need to be. If you want to keep reading about the actual business of technology, we publish every day.